Different Types of Travel Insurance Plans: A Complete Guide for Every Traveler
Traveling is an exciting experience that allows people to explore new destinations, discover different cultures, and create unforgettable memories. Whether you are planning a family vacation, an international business trip, a solo adventure, or a relaxing weekend getaway, preparing for unexpected situations is an important part of the journey. However, even the best travel plans can sometimes face unexpected problems. Flight cancellations, lost luggage, medical emergencies, and travel delays can quickly turn an enjoyable vacation into a stressful experience.
This is where travel insurance becomes valuable. It provides financial protection against certain unexpected events that may happen before or during your trip. Nevertheless, not every insurance policy offers the same benefits. Different types of travel insurance plans are designed to meet different travel needs, budgets, destinations, and personal circumstances.
For example, a person traveling internationally for several weeks may need comprehensive travel insurance with emergency medical coverage. On the other hand, someone taking several short trips throughout the year might benefit from an annual multi-trip policy.
Understanding these options can help you make a better decision. In this guide, we will explore the major types of travel insurance plans, their advantages and disadvantages, coverage options, and the situations in which each policy may be appropriate.
1. What Is Travel Insurance?
Travel insurance is a financial protection product designed to help travelers manage eligible unexpected expenses associated with their trips. Depending on the policy, it may cover medical emergencies, trip cancellations, travel interruptions, baggage problems, flight delays, and other covered incidents.
However, coverage varies significantly between insurance providers and individual policies. Therefore, travelers should always review the policy wording before purchasing protection.
Generally, travel insurance can be purchased for domestic trips, international holidays, business travel, family vacations, and specialized activities.
Most policies provide one or more of the following benefits:
- Emergency medical expenses.
- Emergency medical evacuation.
- Trip cancellation and interruption.
- Lost, stolen, or delayed baggage.
- Travel delay compensation.
- Personal accident coverage.
- Emergency assistance services.
- Certain adventure sports coverage.
Although travel insurance cannot prevent unexpected events, it can reduce their financial impact when a claim meets the policy requirements.
2. Different Types of Travel Insurance Plans
There are several types of travel insurance plans available. Each option serves a particular purpose. Consequently, understanding the differences can help you select suitable coverage.
2.1 Basic Travel Insurance
Itt az újabb Booking-botrány: figyelj oda, adathalászok áldozatává válhatsz
Basic travel insurance is generally designed for travelers who want essential protection without paying for extensive additional benefits.
Depending on the provider, a basic policy may include limited emergency medical coverage, baggage protection, and compensation for certain travel delays.
It is commonly suitable for short vacations, domestic journeys, and travelers who do not require extensive coverage.
Benefits of Basic Travel Insurance
- Usually costs less than comprehensive plans.
- Provides essential protection against selected travel problems.
- Offers a straightforward coverage structure.
- Can be suitable for shorter trips.
- May provide basic emergency assistance.
Pros:
- Affordable for budget-conscious travelers.
- Easier to understand than some extensive policies.
- Suitable for travelers with limited coverage requirements.
Cons:
- Lower coverage limits.
- May exclude expensive medical emergencies.
- Limited cancellation and interruption protection.
- Additional activities may not be covered.
When Should You Choose It?
Consider basic travel insurance when taking a short, relatively simple trip and when you understand that its coverage limits may leave some expenses unpaid.
However, always compare the medical limits and exclusions before selecting the cheapest option.
2.2 Comprehensive Travel Insurance
Urlaub und Reiseversicherung 2025 – Ihr kompletter Leitfaden | Freitime
Comprehensive travel insurance offers broader protection by combining several travel-related benefits into one policy.
It is one of the most popular choices for people planning international vacations, family holidays, and longer journeys.
Depending on the provider, comprehensive coverage may include emergency medical treatment, trip cancellation, trip interruption, baggage loss, travel delays, and emergency evacuation.
Furthermore, some providers offer additional protection for rental vehicles, personal belongings, and selected adventure activities.
Benefits of Comprehensive Travel Insurance
- Broader financial protection.
- Emergency medical coverage.
- Trip cancellation benefits for covered reasons.
- Protection against eligible baggage problems.
- Assistance during unexpected travel disruptions.
Pros:
- Covers multiple travel risks under one policy.
- Convenient for international travelers.
- Can provide higher coverage limits.
- Offers greater flexibility through optional add-ons.
Cons:
- Usually more expensive than basic insurance.
- Some benefits have separate coverage limits.
- Certain pre-existing medical conditions may be excluded.
- Not every cancellation reason qualifies for reimbursement.
When Should You Choose It?
Comprehensive travel insurance is worth considering when you have booked expensive flights, hotels, tours, or international travel arrangements.
Additionally, it may be suitable for families who want several types of protection under a single policy.
2.3 Single-Trip Travel Insurance
Travel Safety Facts vs Fear in 2026 | Wilton Vida — Wilton Vida
Single-trip travel insurance provides coverage for one specific journey. The policy normally begins and ends according to the dates stated in the insurance contract.
It can be purchased for domestic or international travel, depending on the insurance provider.
For example, someone planning a 14-day holiday in Europe may purchase a single-trip policy covering those travel dates.
Benefits:
- Designed for one particular journey.
- Suitable for occasional travelers.
- Allows travelers to select coverage according to their destination.
- Can include medical and cancellation protection.
- Avoids paying for an annual policy when only one trip is planned.
Pros:
- Convenient for occasional vacations.
- Coverage can match the planned travel dates.
- Often suitable for short-term international travel.
Cons:
- A separate policy may be required for every new trip.
- Multiple purchases can become expensive.
- Coverage generally ends after the insured journey.
When Should You Choose It?
Choose single-trip insurance if you travel occasionally and have one main vacation or business journey planned.
It is particularly useful when you want coverage tailored to one destination and travel period.
2.4 Annual Multi-Trip Travel Insurance
Сам себе тревел-менеджер: как эффективно подготовиться к командировке | РБК Life
Annual multi-trip travel insurance is designed for people who travel several times throughout the year.
Instead of purchasing a separate policy for every journey, travelers can obtain coverage for multiple eligible trips during a specified 12-month period.
However, most annual policies include a maximum duration for each individual trip. For instance, a policy may allow 15, 30, or 45 days per journey.
Benefits:
- Covers multiple eligible trips throughout the year.
- Reduces the need to purchase separate policies.
- Convenient for frequent travelers.
- May include medical and baggage protection.
- Can simplify travel insurance management.
Pros:
- Potentially cost-effective for frequent travelers.
- Saves time when planning multiple journeys.
- Provides continuous policy arrangements during the insurance year.
Cons:
- Higher initial payment than some single-trip policies.
- Individual trip-duration limits apply.
- Certain destinations may be excluded.
- Not ideal for people who travel only once.
When Should You Choose It?
Annual multi-trip insurance is suitable for frequent business travelers, consultants, international professionals, and families who take several holidays each year.
Before purchasing, calculate how many trips you expect to take and compare the annual premium with separate single-trip policies.
2.5 Medical Travel Insurance
Medical Treatment in China | Huayitong Medical
Medical travel insurance focuses primarily on healthcare expenses that may occur during a trip.
Medical treatment abroad can be expensive, especially in countries where visitors do not qualify for public healthcare benefits.
This type of insurance may cover eligible hospital visits, emergency treatment, ambulance services, prescribed medication, and emergency medical evacuation.
Nevertheless, coverage depends on the policy and applicable exclusions.
Benefits:
- Financial protection against eligible emergency medical expenses.
- Access to emergency assistance services.
- Potential coverage for hospitalization.
- May include emergency transportation.
- Useful for international destinations with expensive healthcare.
Pros:
- Focuses on an important travel risk.
- Can provide high medical coverage limits.
- Particularly valuable for international trips.
- May include medical evacuation services.
Cons:
- May not include trip cancellation.
- Pre-existing conditions may be excluded or restricted.
- Routine medical appointments may not qualify.
- Certain sports and activities may require additional coverage.
When Should You Choose It?
Consider medical travel insurance when traveling internationally, particularly to destinations where medical services are expensive.
Older travelers and people who require access to healthcare during their journeys should carefully examine the eligibility requirements and exclusions.
2.6 Trip Cancellation Insurance
Trip cancellation insurance is designed to reimburse eligible prepaid and non-refundable travel expenses when a covered event forces you to cancel your journey before departure.
Unexpected illness, serious injury, certain family emergencies, and other specifically listed events may qualify, depending on the policy.
For example, imagine booking an expensive international vacation several months in advance. If a covered medical emergency prevents you from traveling, cancellation insurance may help recover eligible prepaid costs.
Benefits:
- Protects certain prepaid travel expenses.
- Helps reduce financial losses.
- May cover eligible hotel and flight cancellations.
- Can provide additional protection for expensive holidays.
Pros:
- Useful for expensive travel arrangements.
- Provides financial protection before departure.
- May cover several specified cancellation circumstances.
Cons:
- Only listed covered reasons qualify under standard policies.
- Documentation may be required.
- Some policies exclude known events or circumstances.
- Optional Cancel For Any Reason (CFAR) coverage costs extra and has restrictions.
When Should You Choose It?
Choose trip cancellation coverage when you have booked expensive, non-refundable flights, accommodation, cruises, or holiday packages.
Furthermore, consider purchasing it soon after making your initial travel deposit because some optional benefits have strict purchase deadlines.
2.7 Baggage and Personal Belongings Insurance
Baggage insurance provides financial protection against certain problems involving your luggage and personal belongings.
These incidents may include theft, accidental loss, damage, or baggage delays.
For example, if an airline delays your checked luggage, your policy may reimburse eligible essential purchases within the stated limits.
Benefits:
- Protection against covered baggage loss.
- Possible compensation for damaged luggage.
- Assistance with delayed baggage.
- Coverage for selected personal belongings.
Pros:
- Helpful when carrying valuable travel items.
- Can reduce unexpected replacement expenses.
- Provides additional peace of mind.
Cons:
- Individual item limits may apply.
- High-value electronics may require additional protection.
- Some valuable belongings may be excluded.
- Proof of ownership and airline reports may be necessary.
When Should You Choose It?
Baggage insurance is worth considering when carrying expensive luggage, cameras, laptops, professional equipment, or other valuable personal belongings.
However, check whether your existing home or personal property insurance already covers your possessions during travel.
2.8 Business Travel Insurance
Starryblu vs Charles Schwab Debit Card: Best for Cross-Border Money Management?
Business travel insurance is designed for employees, entrepreneurs, consultants, and professionals who travel for work.
Unlike ordinary vacation insurance, business travel policies may include additional benefits related to professional equipment and work-related travel disruptions.
Depending on the provider, coverage may include medical emergencies, trip cancellation, baggage protection, business equipment, and travel assistance.
Benefits:
- Protection during eligible business journeys.
- Possible coverage for laptops and professional equipment.
- Emergency medical assistance.
- Protection against certain travel interruptions.
- Optional coverage for business-related expenses.
Pros:
- Designed around professional travel requirements.
- Useful for frequent business travelers.
- May protect essential work equipment.
- Can be arranged through an employer.
Cons:
- May cost more than basic vacation insurance.
- Work equipment may have separate limits.
- Certain business activities may be excluded.
- Not all professional expenses qualify for reimbursement.
When Should You Choose It?
Business travel insurance is suitable for employees attending conferences, international meetings, training programs, and corporate events.
Companies that regularly send employees overseas should also review group business travel insurance options.
2.9 Adventure and Sports Travel Insurance
The differences between trekking and mountaineering | Inwild.co.uk
Adventure travel insurance is designed for people participating in activities that may involve increased physical risks.
Examples include skiing, scuba diving, mountain climbing, trekking, surfing, and certain extreme sports.
Standard travel insurance policies may exclude some of these activities. Therefore, specialized coverage may be necessary.
Benefits:
- Protection for selected adventure activities.
- Possible emergency medical coverage.
- Emergency rescue and evacuation benefits.
- Coverage for qualifying sports equipment.
- Additional assistance during adventure trips.
Pros:
- Better suited to active travelers.
- Can cover activities excluded from ordinary policies.
- Provides specialized emergency assistance.
Cons:
- Often more expensive.
- Dangerous activities may still be excluded.
- Altitude and experience restrictions may apply.
- Professional competitions may require separate insurance.
When Should You Choose It?
Consider adventure travel insurance if your itinerary includes mountain climbing, skiing, scuba diving, or other higher-risk activities.
Before buying, confirm that every planned activity is specifically included in the policy.
2.10 Senior Citizen Travel Insurance
Élmények, ízek, nyelvi kihívások: így utazzunk Ázsiába magabiztosan 50 felett | Rúzs online
Senior citizen travel insurance is designed for older travelers who may face different healthcare and travel-related requirements.
Some providers offer specialized policies with medical coverage, emergency hospitalization, evacuation, and selected pre-existing medical condition benefits.
However, age restrictions, medical declarations, and coverage limits vary between providers.
Benefits:
- Coverage options designed for older travelers.
- Potential emergency medical assistance.
- Selected pre-existing condition coverage.
- Protection against certain travel interruptions.
Pros:
- Addresses the needs of older travelers.
- May offer specialized medical benefits.
- Provides access to emergency support.
Cons:
- Premiums may be higher.
- Some age limits apply.
- Medical conditions may require additional declarations.
- Certain treatments may be excluded.
When Should You Choose It?
Senior travel insurance is worth considering for older adults planning international holidays, family visits, or extended journeys.
Always disclose relevant medical information accurately and check the policy’s age and medical eligibility requirements.
2.11 Student Travel Insurance
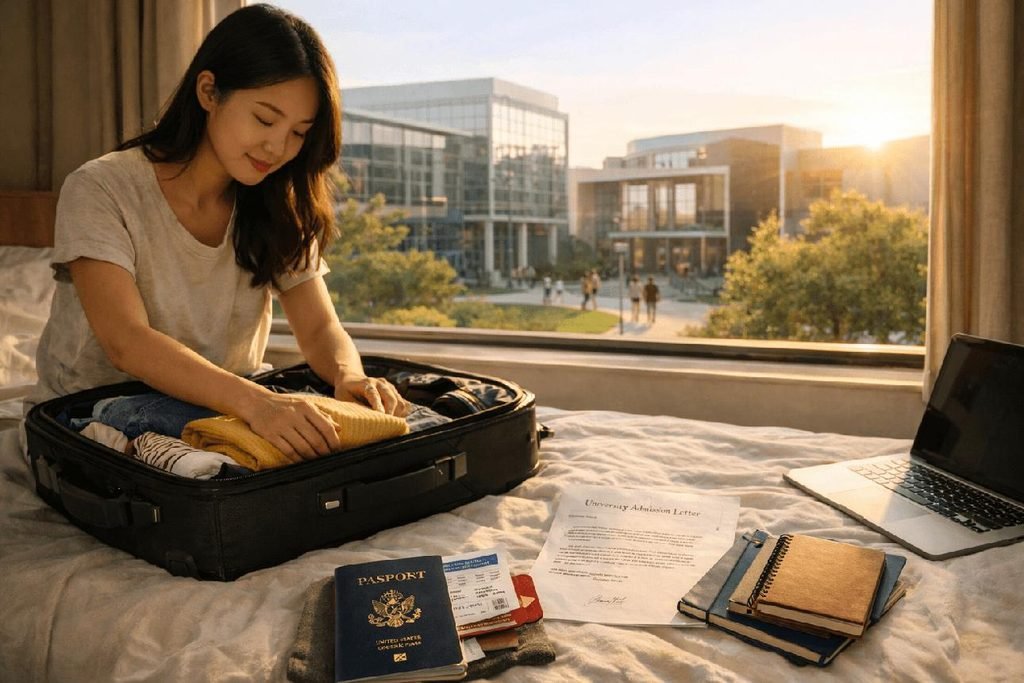
Pre-Departure Checklist for Students Going Abroad in 2026 | Study Abroad Courses
Student travel insurance is designed for students traveling abroad for education, exchange programs, internships, or extended academic stays.
Depending on the policy, it may provide medical protection, personal belongings coverage, emergency transportation, and travel interruption benefits.
Some plans also provide coverage for study-related equipment.
Benefits:
- Protection during international education journeys.
- Emergency medical coverage.
- Personal belongings protection.
- Coverage options for longer stays.
- Potential emergency travel assistance.
Pros:
- Designed for student travel requirements.
- Can cover longer educational journeys.
- Useful for exchange and study-abroad programs.
Cons:
- Some policies have maximum age limits.
- University insurance requirements may differ.
- Not every plan covers internships or paid employment.
- Certain activities may be excluded.
When Should You Choose It?
Students planning to study abroad should compare student travel insurance with the health insurance requirements of their destination university.
Additionally, check whether the institution requires specific medical coverage limits.
2.12 Family Travel Insurance
How to Make Family Vacations Less Stressful (and Actually Enjoyable)
Family travel insurance provides protection for multiple eligible family members under one policy.
Depending on the insurer, it may cover parents and dependent children traveling together.
Common benefits include emergency medical expenses, cancellation protection, baggage coverage, and travel delays.
Benefits:
- One policy for multiple family members.
- Convenient travel insurance management.
- Coverage for eligible children.
- Potential savings compared with separate policies.
Pros:
- Simplifies insurance arrangements.
- Suitable for family vacations.
- Can offer comprehensive protection.
- Reduces the need to manage multiple individual policies.
Cons:
- Family eligibility rules apply.
- Coverage limits may be shared or individual.
- Age restrictions may apply to dependent children.
- Not every family member may qualify automatically.
When Should You Choose It?
Family travel insurance is suitable for parents traveling with children, particularly when planning international vacations or expensive family holidays.
Check whether every family member is included and whether the policy covers children traveling separately.
3. Comparison of Different Travel Insurance Plans
Choosing the right travel insurance becomes easier when you compare the main features of each option.
| Insurance Type | Main Coverage | Best For |
|---|---|---|
| Basic | Essential travel protection | Budget travelers |
| Comprehensive | Multiple travel risks | International vacations |
| Single-trip | One journey | Occasional travelers |
| Annual multi-trip | Multiple journeys | Frequent travelers |
| Medical | Emergency healthcare | International trips |
| Trip cancellation | Covered prepaid expenses | Expensive holidays |
| Baggage | Lost, stolen, or delayed luggage | Travelers with valuables |
| Business | Work-related travel risks | Professionals |
| Adventure | Selected sports and activities | Adventure travelers |
| Senior citizen | Specialized travel and medical needs | Older travelers |
| Student | Educational travel | International students |
| Family | Multiple eligible family members | Family vacations |
Remember that these categories can overlap. For example, a family may purchase comprehensive single-trip insurance, while a business traveler may choose annual multi-trip medical coverage.
4. How to Choose the Right Travel Insurance Plan
Selecting travel insurance should depend on your destination, travel duration, budget, health requirements, and planned activities.
Here are some important factors to consider.
4.1 Understand Your Destination
Different destinations have different healthcare costs, travel risks, and insurance requirements.
For example, emergency medical treatment in certain international destinations can be expensive. Therefore, travelers should consider higher medical coverage limits when necessary.
Additionally, check whether your destination requires proof of travel medical insurance for a visa application.
4.2 Consider Your Travel Duration
The length of your journey can influence the type of insurance you need.
Single-trip insurance may be appropriate for a short vacation. However, annual multi-trip coverage could be more convenient if you regularly travel throughout the year.
For longer stays, check maximum trip-duration limits and whether long-stay insurance is available.
4.3 Evaluate Your Health Requirements
Medical coverage is an important consideration, particularly for international travelers.
Check emergency treatment limits, medical evacuation benefits, pre-existing condition exclusions, and prescription medication rules.
Most importantly, provide accurate information when completing your insurance application.
4.4 Compare Coverage Limits
Do not choose a policy based on price alone.
Instead, compare:
- Emergency medical coverage.
- Medical evacuation limits.
- Cancellation reimbursement limits.
- Baggage protection limits.
- Travel delay benefits.
- Personal accident coverage.
- Deductibles and excess amounts.
A cheaper policy may have significantly lower limits or more exclusions.
4.5 Review Policy Exclusions
Every insurance policy includes conditions under which claims may be rejected.
Common exclusions can include:
- Certain pre-existing medical conditions.
- Undeclared adventure activities.
- Traveling against medical advice.
- Certain high-risk events.
- Unattended baggage.
- Claims without required documentation.
- Events already known when purchasing coverage.
Therefore, read the policy wording carefully before making a payment.
4.6 Check Emergency Assistance Services
Reliable emergency assistance can be extremely helpful when facing problems in another country.
Look for insurers that provide 24-hour emergency support, medical coordination, and clear instructions for making claims.
Also, save the emergency contact number and policy documents before departure.
5. Common Travel Insurance Mistakes to Avoid
Even experienced travelers sometimes make mistakes when purchasing travel insurance.
Avoiding these common problems can help you select more suitable protection.
1. Choosing the Cheapest Policy
Low-cost insurance may offer limited benefits. Therefore, compare coverage limits and exclusions rather than focusing entirely on price.
2. Ignoring Medical Coverage
Medical treatment abroad can be expensive. Make sure your policy provides suitable emergency medical and evacuation benefits.
3. Buying Insurance Too Late
Some cancellation and optional benefits have purchase deadlines. Consequently, buying insurance soon after making your first non-refundable travel payment may be beneficial.
4. Providing Incorrect Information
Incorrect medical declarations or travel details can create problems during claims. Always provide accurate information.
5. Forgetting Adventure Activities
If you plan to ski, dive, climb, or participate in other activities, confirm that your policy specifically covers them.
6. Not Reading the Policy Documents
Marketing descriptions do not explain every condition. Read the complete policy wording before purchasing.
7. Assuming Every Cancellation Is Covered
Standard trip cancellation insurance generally covers only specified reasons. Optional CFAR coverage may provide broader cancellation flexibility but usually reimburses only a percentage of eligible costs and has strict conditions.
6. Is Travel Insurance Worth Buying?
Travel insurance can be a valuable investment because unexpected problems can create significant expenses.
Imagine that you are traveling internationally and suddenly require emergency hospitalization. Without suitable insurance, you may have to pay substantial medical bills yourself.
Similarly, a covered emergency could force you to cancel an expensive vacation. A suitable cancellation policy may help recover eligible non-refundable costs.
However, insurance is not equally necessary for every traveler or every trip. Your decision should depend on the potential financial loss, existing insurance benefits, destination requirements, and personal circumstances.
Before purchasing a policy, compare several providers and carefully examine the benefits, exclusions, deductibles, and claim procedures.
Ultimately, the right travel insurance plan is one that protects you against the risks that matter most during your journey.
7. Final Thoughts
Understanding the different types of travel insurance plans is an important part of preparing for a safe and comfortable journey.
From basic and comprehensive coverage to medical, annual multi-trip, student, family, and adventure insurance, every option serves a different purpose.
For occasional travelers, single-trip insurance may be sufficient. Meanwhile, frequent travelers may benefit from annual coverage. Families might prefer a shared family policy, whereas international students and older adults may need specialized protection.
Most importantly, do not purchase a policy simply because it is inexpensive. Compare the coverage limits, exclusions, medical benefits, and emergency assistance services before making your decision.
With proper planning and suitable insurance protection, you can travel with greater confidence and focus on enjoying your destination.
Frequently Asked Questions (FAQs)
The main types include basic travel insurance, comprehensive insurance, single-trip insurance, annual multi-trip insurance, medical travel insurance, trip cancellation insurance, baggage insurance, business insurance, adventure insurance, student insurance, senior citizen insurance, and family insurance.
Comprehensive travel insurance is a popular option for international travel because it can combine medical emergencies, evacuation, trip cancellation, baggage protection, and travel delays. However, the best option depends on your destination and individual requirements.
Single-trip insurance covers one specific journey. In comparison, annual multi-trip insurance covers multiple eligible journeys during a 12-month policy period, subject to individual trip-duration limits.
Time needed: 9 minutes
Travel insurance can provide valuable protection for international students, particularly for emergency medical treatment, personal belongings, and travel interruptions. Some universities and countries also require specific health insurance arrangements.
- Is comprehensive travel insurance worth the extra cost?
Comprehensive travel insurance can be worthwhile when you have expensive prepaid bookings, international medical risks, or several travel arrangements to protect. Compare the additional benefits with the price difference before purchasing.
Perfect For:
Personal Finance Management
Family Budget Planning
Students & Professionals
Freelancers & Small Business Owners
Daily Expense Tracking
Savings & Financial Goal Management
Download > Expense Finance Tracker pro
https://play.google.com/store/apps/details?id=com.app.ExpenseFinanceTrackerPro&pcampaignid=web_share